


Essential Points
- Investment diversification involves spreading your capital across different assets, sectors, and countries so that the failure of one does not drag down everything else.
- The secret is not having many things, but having things that don't move the same way: the correlation between assets is what determines if you are truly diversified.
- A single global ETF can give you exposure to approximately 1.500 companies in 23 countries with an annual fee of less than 0,25%.
- Diversification reduces the specific risk of an asset, but does not eliminate the risk of the market as a whole: it is the most powerful tool of the sensible investor, not a guarantee.
When someone starts to consider how to invest their money, they almost always arrive at the same question: Where do I put it? The most honest answer any financial professional can give isn't a company name or a specific country, but a strategy: spread it out. Investment diversification has been the top recommendation in any serious personal finance manual for decades, and that's no coincidence. In a world where no asset, company, or market is immune to unforeseen events, distributing risk is the smartest way to protect what you've built.
In this article we explain what diversification is, how it works in practice, what tools are available to you from Spain, and how to avoid the most common mistakes made by those who believe that diversifying is simply having "many things"If you already own crypto assets and want to understand how they fit into a broader portfolio, you'll also find a specific section for you here.
What is diversification and why does it matter?
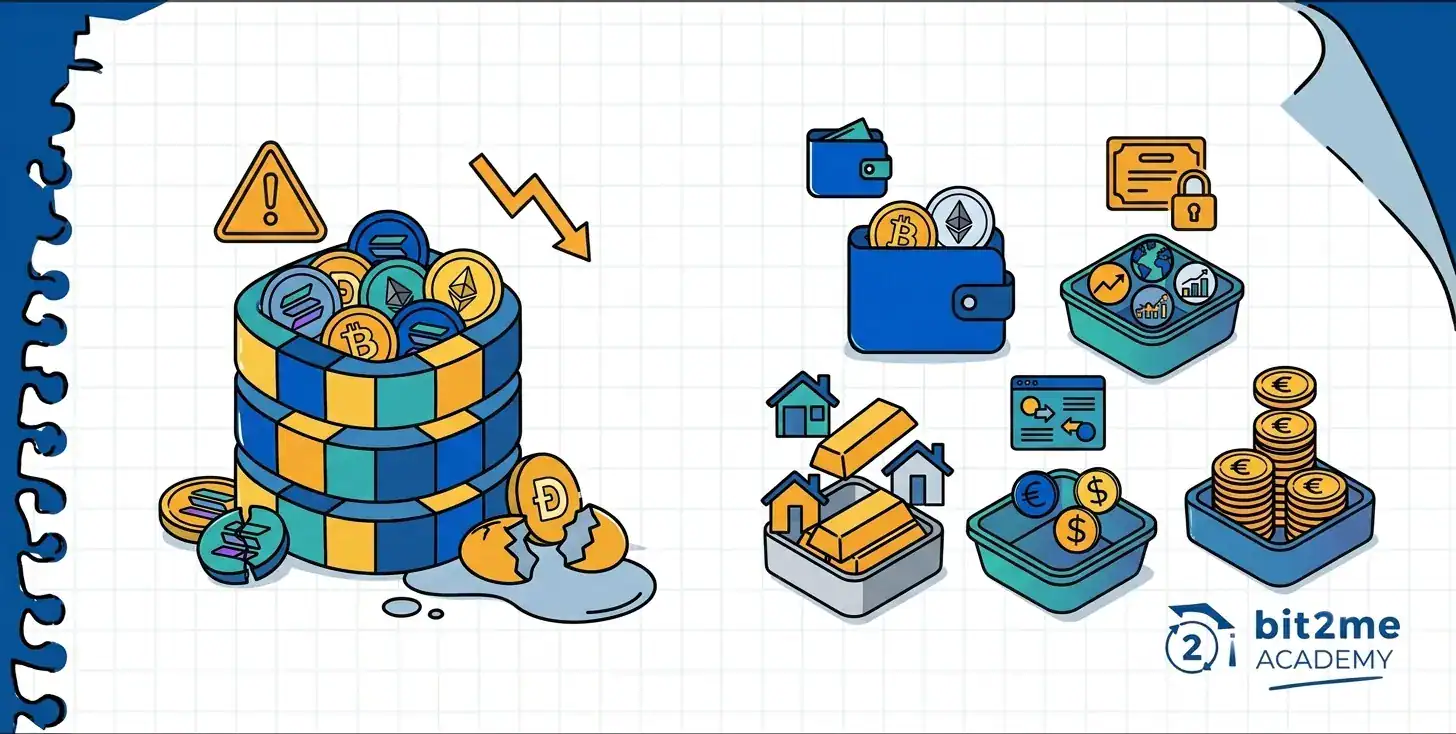
The proverb sums it up better than any textbook: don't put all your eggs in one basket. If you have all your capital invested in the shares of a single Spanish company and that company goes into crisis, your entire portfolio suffers the blow. However, if you have that same capital spread across hundreds of companies in different countries and sectors, the collapse of just one of them will barely be felt overall.
That, in essence, is investment diversification: distributing capital across multiple assets so that the poor performance of one doesn't drag down the entire portfolio. Diversification mitigates what in finance is called specific or unsystematic risk: the risk associated with a particular company, sector, or country. By spreading your investments across many assets, you reduce that risk to almost nothing. What diversification cannot eliminate, however, is systematic risk, the risk of the global market as a whole: when markets fall worldwide simultaneously, all assets are affected to a greater or lesser degree.
Understanding this distinction is important because it sets realistic expectations. Diversification isn't a magic formula that prevents all losses; it's a way to prevent a localized setback from becoming a catastrophe for your assets.
The three pillars of diversification
Proper diversification operates on at least three distinct dimensions. One of these axes alone is not enough; real protection comes from combining them.
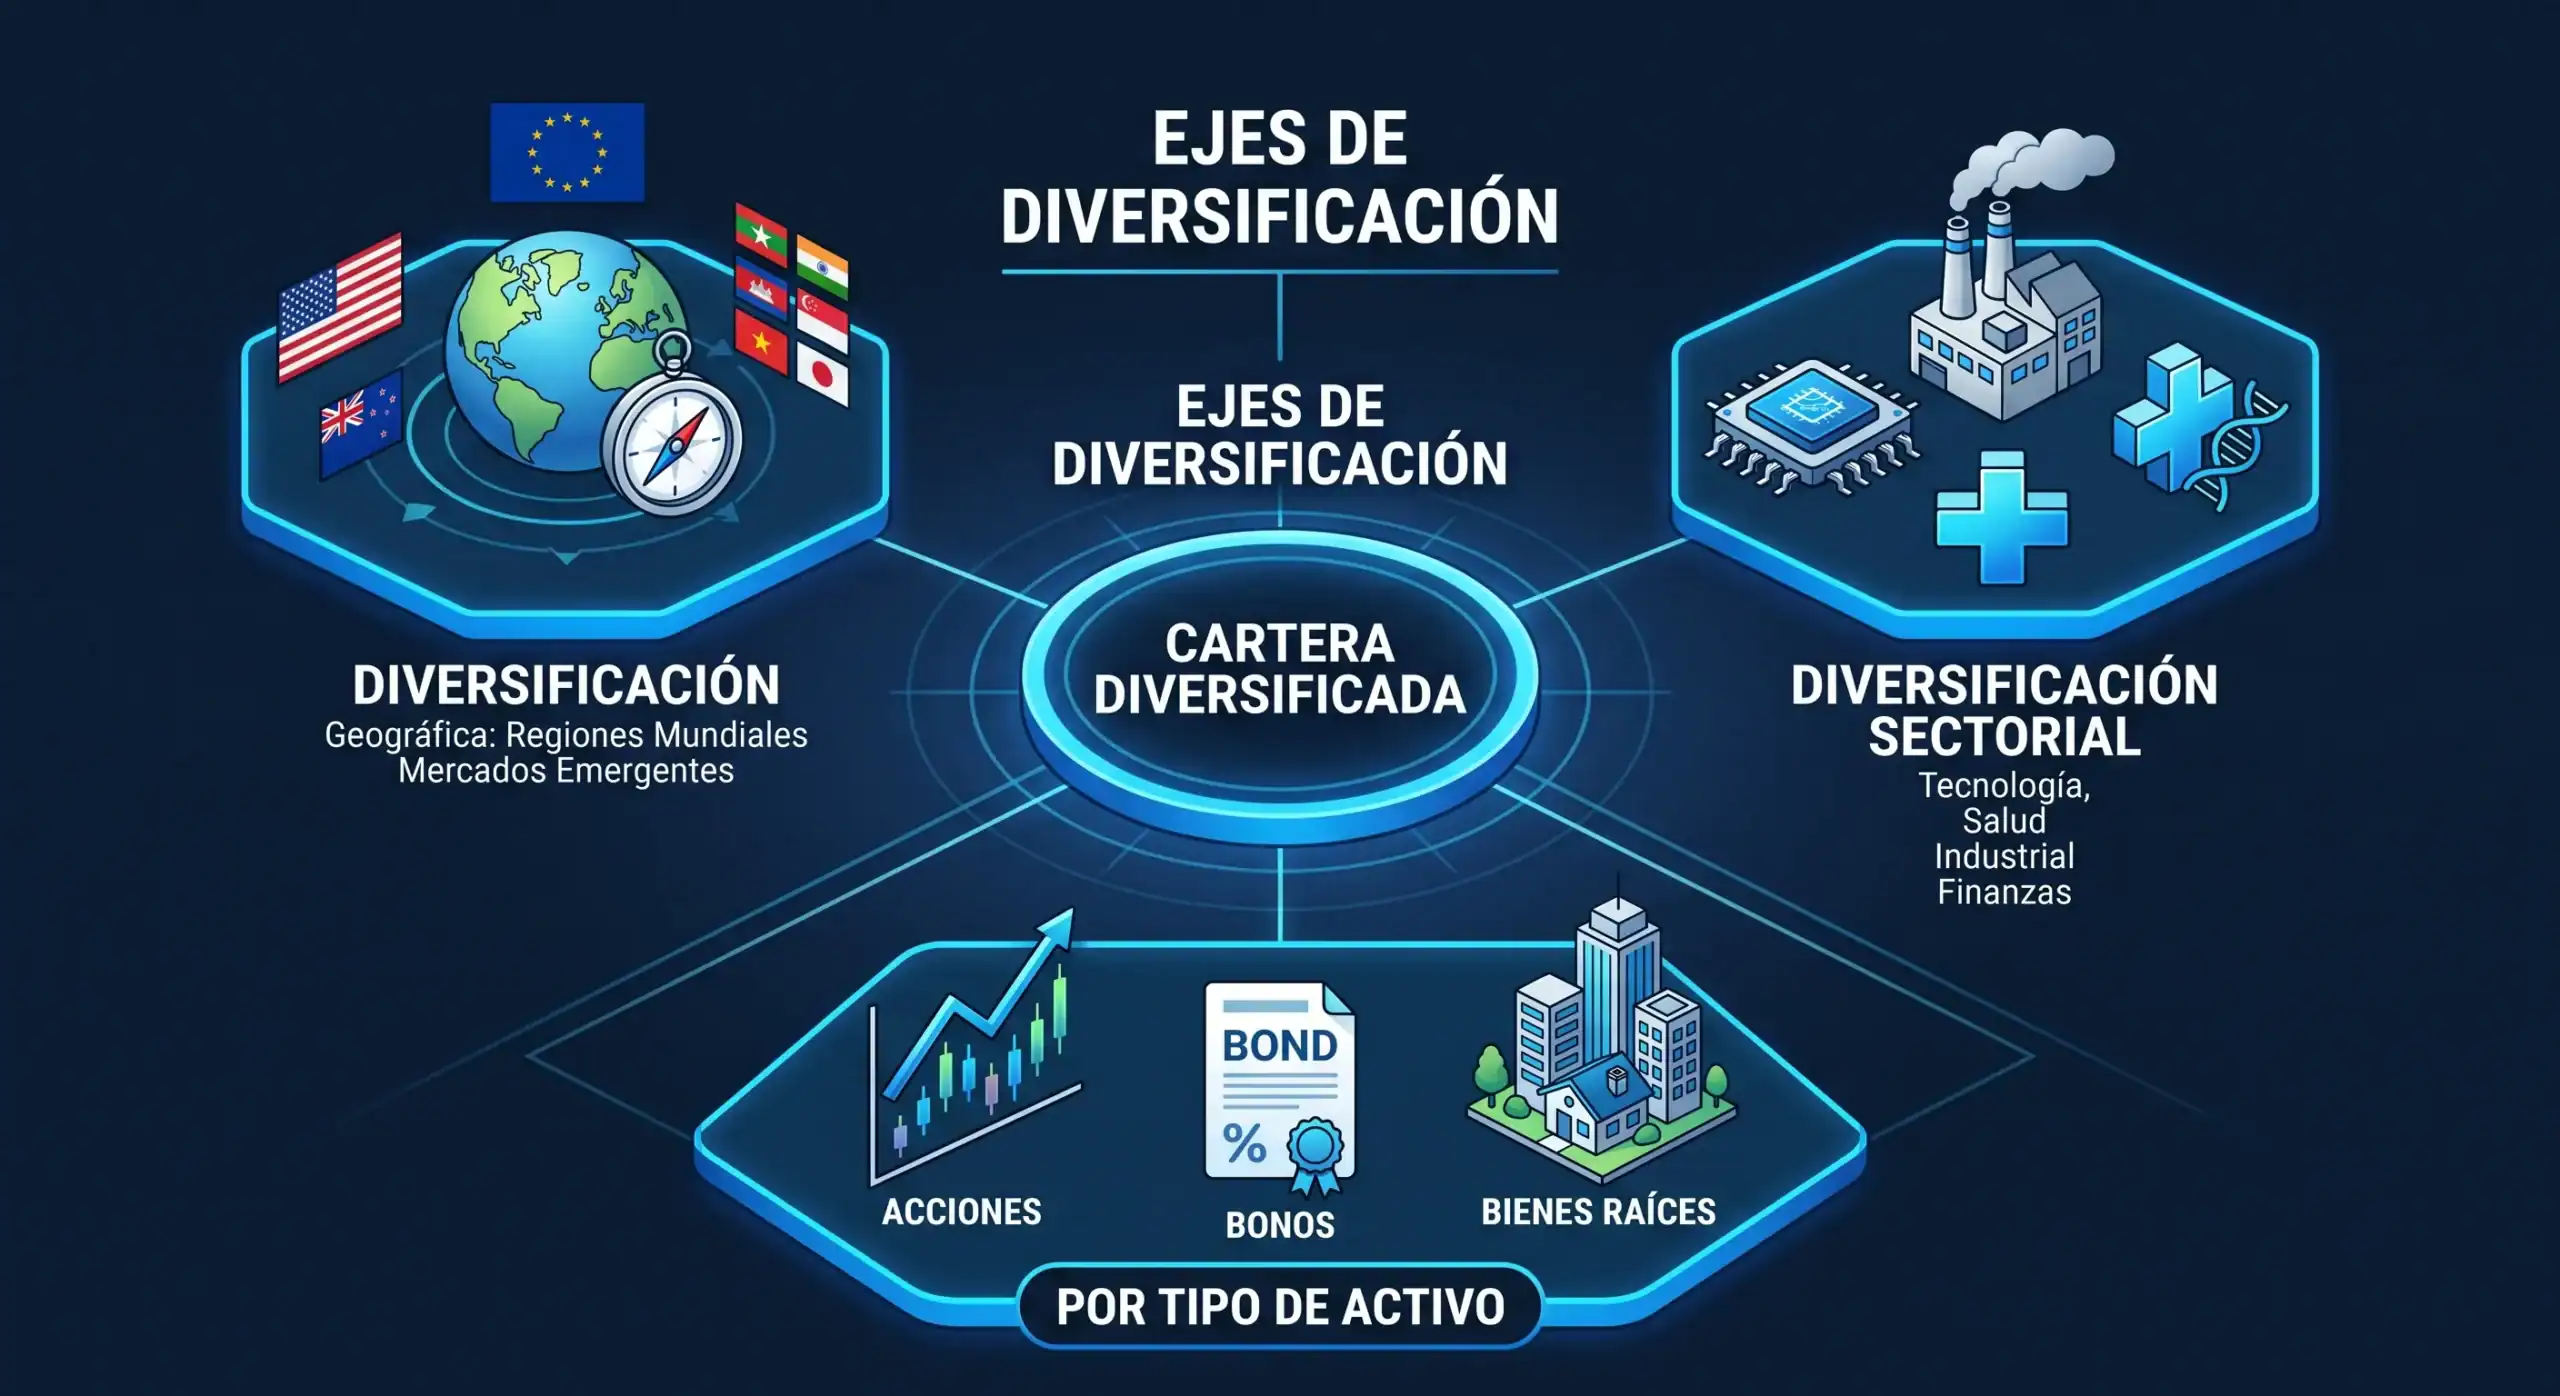
- Geographic diversification. Concentrating all your investment in Spain, or even in Europe, is taking on unnecessary geographical risk. The Spanish economy can be affected by factors that don't impact the United States, Japan, or emerging Asian markets in the same way. Global indices like the MSCI World, which tracks approximately 1.500 companies from 23 developed countries, do this automatically with a single position.
- Sectoral diversification. If your entire portfolio is in technology, a downturn in the tech sector will hit you hard. A well-diversified portfolio combines sectors with different economic cycles: energy, healthcare, consumer staples, industrials, and financials. When some sectors suffer, others can remain stable or even grow.
- Diversification by asset type. The third pillar combines assets with different behaviors: equities (stocks and ETFs, with higher return potential and greater volatility), fixed income (bonds and debt funds, more stable but with lower potential returns), and alternative assets or cash. The proportion between these three blocks depends on your investor profile and how much time you have available, a topic we explore in detail in our article on risk and return.
Correlation between assets: the secret ingredient of diversification
This is where many novice investors make the most common mistake. They believe that having ten different funds is good diversification, without realizing that all those funds invest in the same market and move in virtually the same way.
The key to true diversification is not the number of assets, but their correlation. Correlation measures the degree to which two assets move similarly. If two assets are perfectly correlated (they always rise and fall at the same time and in the same proportion), owning both adds no protection. However, if they have a low or negative correlation (when one rises, the other falls, or they move independently), combining them does reduce overall risk.
A concrete example: ten Spanish equity funds that track the Ibex 35 have a very high correlation with each other. If the Ibex falls by 15%, they all fall by roughly the same amount. You haven't diversified; you've multiplied your position. In contrast, combining a global equity fund with a quality fixed-income fund reduces correlation and smooths portfolio volatility, because historically, quality bonds and equities don't always fall at the same time or with the same intensity.
You don't need to know the mathematical correlation coefficients to apply this principle. Simply ask yourself: do these assets depend on the same factors? If the answer is yes, they are probably highly correlated and not as diversified as they appear.
How to diversify with ETFs and index funds
The good news is that effective diversification has never been easier or cheaper. ETFs (exchange-traded funds) and index funds have democratized access to portfolios that were previously reserved for the very wealthy.
An ETF that tracks the MSCI World Index gives you simultaneous exposure to approximately 1.500 companies across 23 developed countries with a single purchase. The annual cost of this type of product—measured by the TER (Total Expense Ratio)—is typically less than 0,25%. This means that for every €10.000 invested, you pay less than €25 per year in fees, compared to the €100-€250 or more that actively managed funds can cost. If you'd like to learn more about these investment vehicles, you can find all the details in our [link to relevant section]. A complete guide on what an ETF is.
Index funds work similarly, but without real-time stock market trading: their price is calculated at the close of each trading session. Both are instruments designed for long-term investors who want broad diversification, low costs, and without the need to select individual companies.
En Bit2Me Invest, through Bit2Me Stocks SL, as a linked agent of InbestMe, an entity supervised by the CNMV, allows you to access ETFs and global index funds from Spain with the regulatory backing of the European securities market.
What about crypto assets? Crypto diversification + traditional assets
Bit2Me It has a unique position in the Spanish market: it allows users to manage both crypto assets and investments in traditional funds and ETFs from a single platform. This raises a legitimate question for those already exposed to crypto assets: do they make sense within the context of a diversified portfolio?
The answer isn't simple, but historical evidence offers some clues. Cryptocurrencies like Bitcoin have shown varying correlations with traditional equities over time. In some periods, this correlation has been low, which could offer some diversification; in other periods, especially during sharp market downturns, the correlation has tended to increase, and cryptocurrencies have fallen along with equities. This makes them a more complex and unpredictable diversification tool than traditional assets.
What is clear is that cryptocurrencies exhibit significantly higher volatility than conventional equities or fixed income. Those considering adding cryptocurrency exposure to a broader portfolio typically do so with modest proportions, usually between 5% and 10% of the total, as an educational guide rather than a personalized recommendation.
 Certificate
The most common mistakes when diversifying
Understanding diversification theory is only half the battle. The other half is avoiding the practical mistakes that even seasoned investors make.
- Illusory diversification. Having ten different Spanish equity funds is not diversification: they all depend on the performance of the Spanish market. True diversification requires assets with different behaviors, not just different names.
- Over-diversification. The opposite extreme also exists. Holding 50 different assets can dilute a portfolio so much that it becomes difficult to manage, generates additional costs, and ultimately replicates the market without the advantages of a clear strategy. More isn't always better.
- Do not review the distribution. A well-diversified portfolio today can become undiversified in a couple of years if you don't review it. If equities rise significantly and fixed income falls, the weight of each asset class changes, and the portfolio becomes riskier than planned. Periodic rebalancing (adjusting the allocation to return to the target percentages) is an essential part of any serious investment strategy.
- Ignoring the time horizon. A very conservative portfolio (high in fixed income, low in equities) for a 30-year horizon can be just as big a mistake as the opposite. Optimal diversification doesn't exist in the abstract: it exists in relation to your time and your goals.

Frequently asked questions about investment diversification



 Author



