Essential Points
- In Spain, several crypto cards coexist, and none of them solves cashback, fees, availability and security all at the same time.
- Every crypto card depends on a regulated electronic money entity that issues the card and processes each payment, not just the platform that markets it.
- It allows you to convert your cryptocurrency balance into real day-to-day spending, without having to manually sell before each purchase.
- The biggest risk is not the technology, but choosing only the highest cashback offer without first checking fees, limits, and who is responsible if something goes wrong.
More and more people in Spain are holding part of their balance in cryptocurrencies and want to use them for everyday payments without going through a manual sales process every time they need to spend. In response to this need, several crypto card options are now available on the market, each with its own issuer, its own method for converting cryptocurrencies into euros, and its own cashback policy. Choosing between them without a clear understanding can lead to decisions based on advertising headlines rather than verifiable data about who processes each payment, what fees apply, and what the actual limits are.
Before choosing an option, it's helpful to understand what questions to ask yourself and what information to request from any provider before applying for the card. In this article, we review the objective criteria that define the best crypto card in Spain for your specific usage profile: who is behind the issuance, how the conversion between cryptocurrencies and euros works, what to realistically expect from cashback, what to look for in terms of availability and limits, and what security guarantees to seek. The goal is not to single out a winner among brands, but to offer you an evaluation template that you can apply to any crypto card you are considering, including the one from [company name missing]. Bit2Me.
Within the European Union's regulatory framework, the MiCA (Markets in Crypto-Assets) regulation requires cryptocurrency service providers to clearly inform users about the associated risks before they use their services. This should be kept in mind when evaluating any cryptocurrency card available in Spain, regardless of the issuing entity.
 Certificate
Why aren't all crypto cards the same?
All crypto cards promise the same thing on the surface: converting your cryptocurrency balance into real-world payments, whether in physical stores or online. However, beneath this common promise lie structural differences that only become apparent when you read the fine print of each provider. The card issuer, the conversion rate, the fee structure, the cashback program, and the spending limits are all independent variables, and no single card automatically excels in every aspect.
Therefore, any serious crypto card comparison should be built on objective and verifiable criteria, not on catchy headlines about cashback percentages or zero fees. A high cashback percentage doesn't compensate for a high conversion spread, just as an attractive physical card is of little use if the issuer behind it isn't clearly identified. Separating each criterion and evaluating it individually is the only way to compare without being swayed by the loudest argument.
If you already know how a crypto card generally works—what it is, how it connects your balance to a real payment, and what role the issuer plays—this guide builds upon the complete guide to crypto cards from Bit2Me Academy and delves specifically into how to evaluate them before deciding. Here we don't repeat those basic concepts, but instead focus on the choice process itself.
Who actually issues the card and why does it matter?
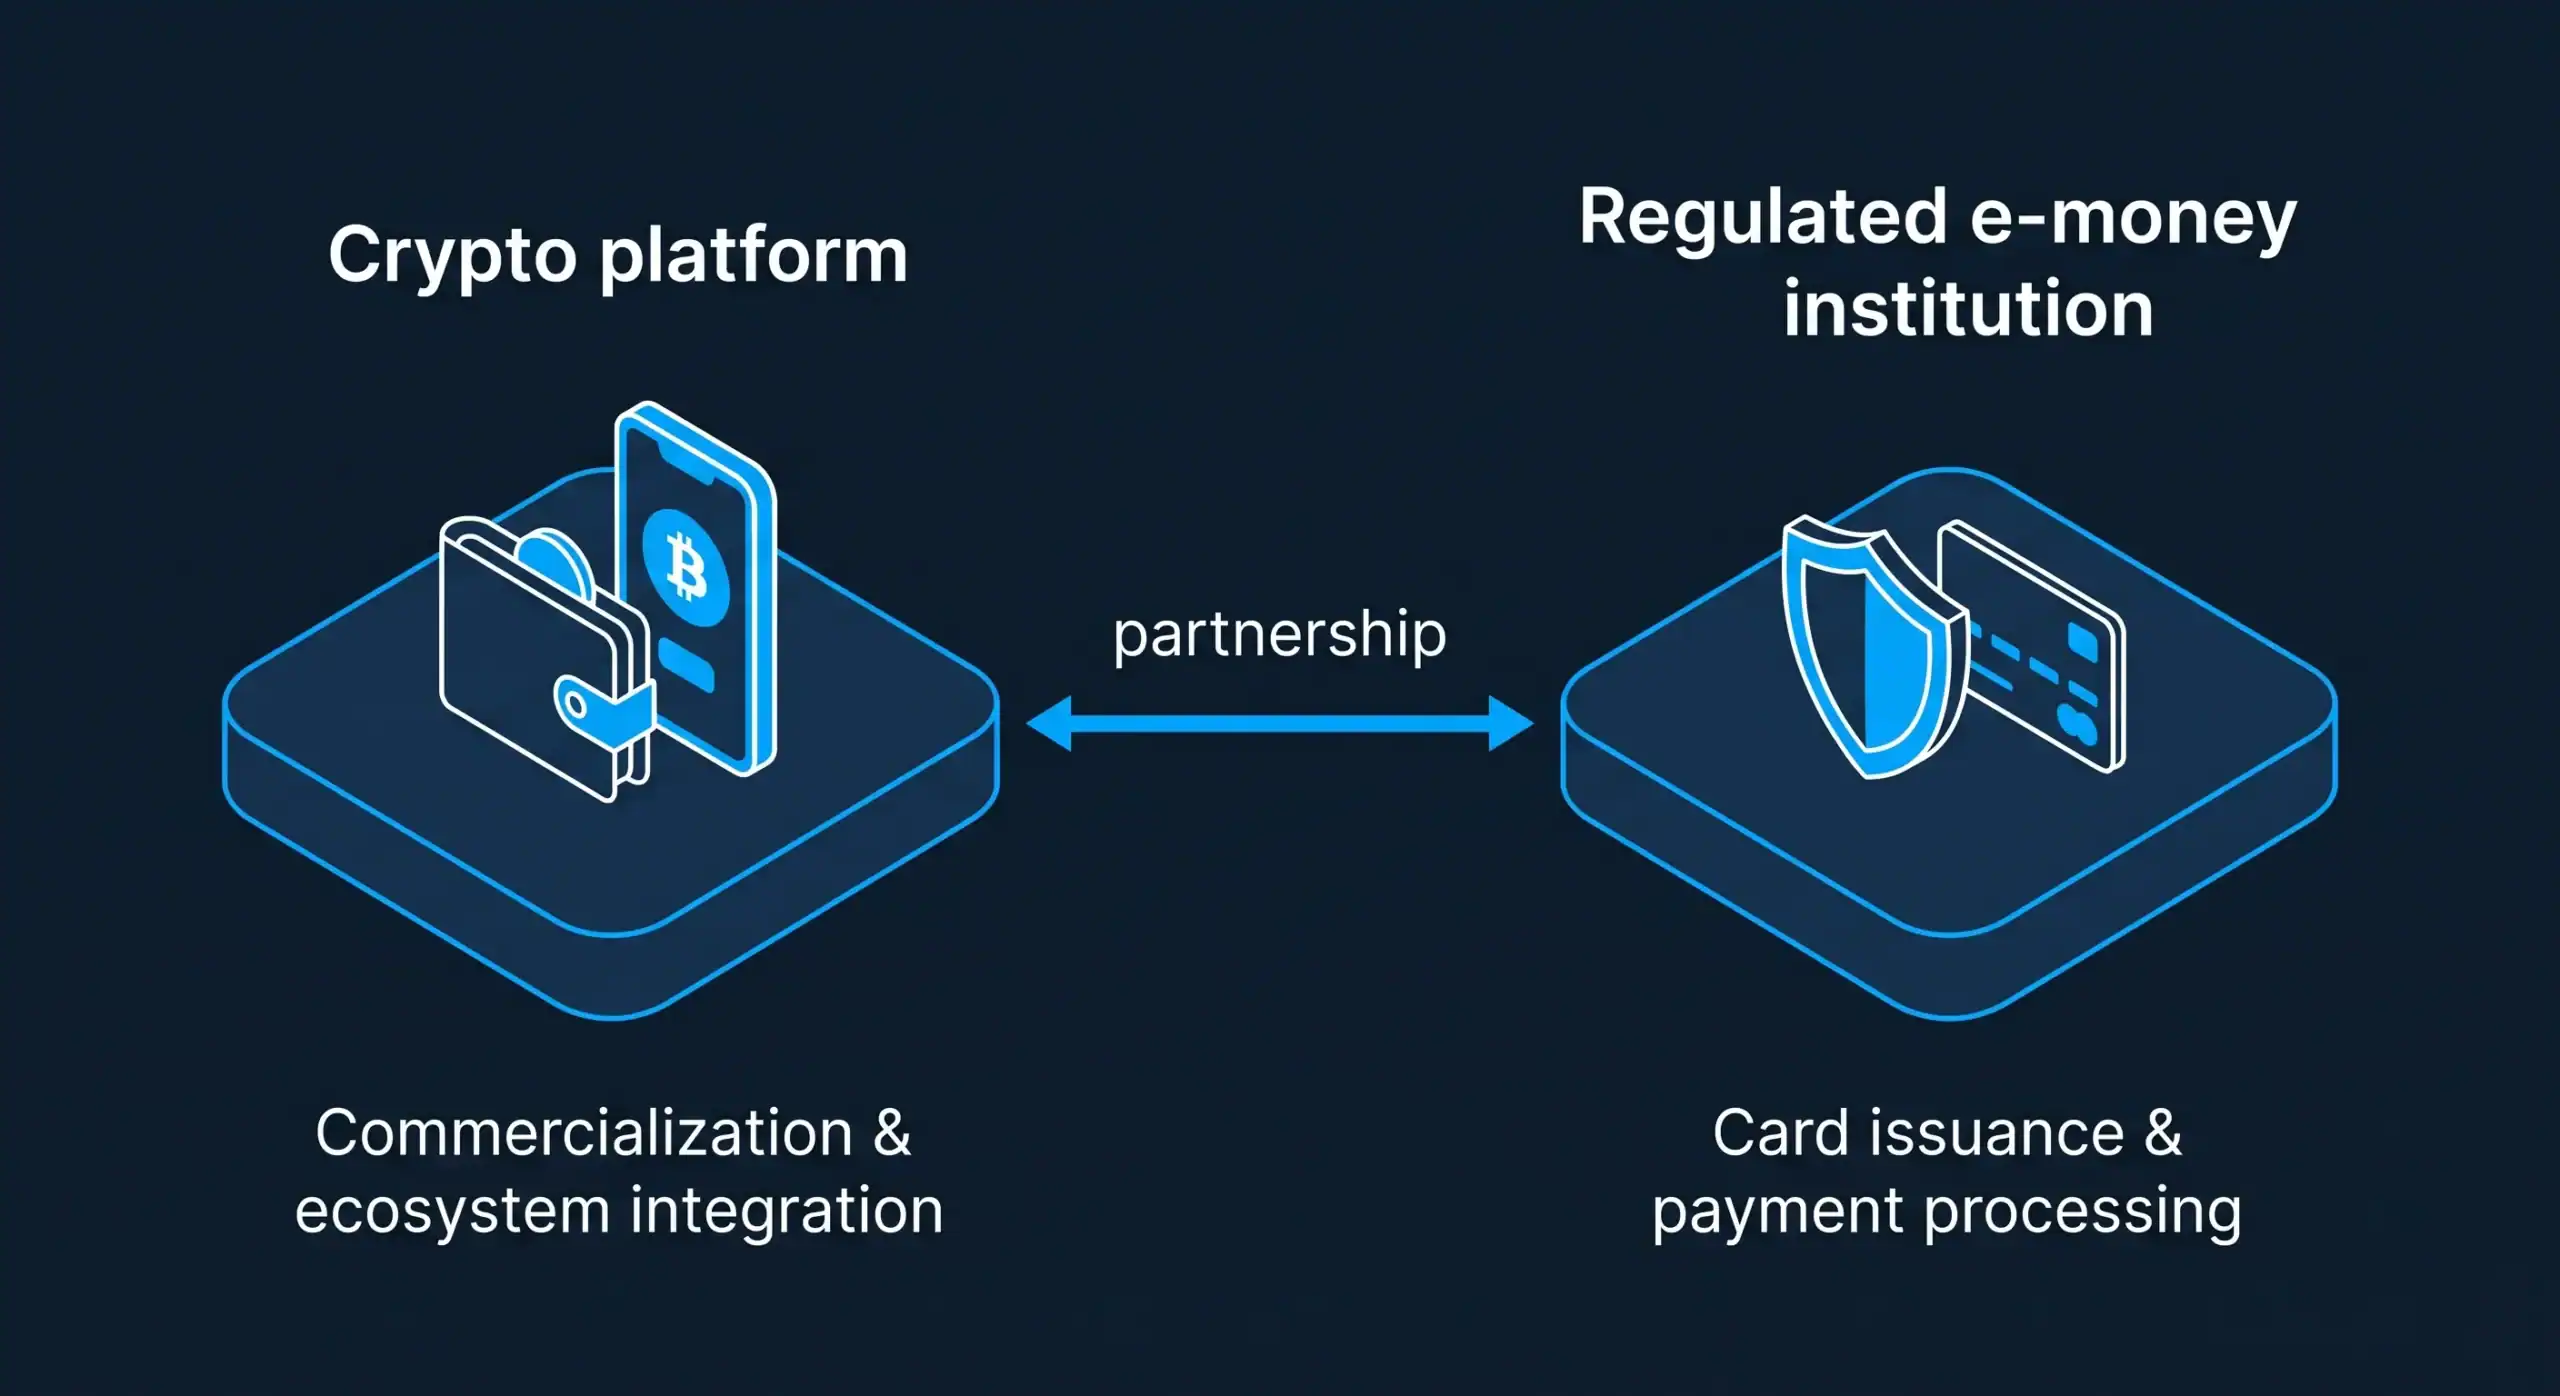
Before you focus on cashback or the card's design, the first question you should ask yourself is who actually issues the product you're considering. No crypto platform issues payment cards itself: issuance and payment processing always fall to a regulated electronic money institution (EMI), while the crypto platform simply markets and integrates that experience within its own ecosystem. This distinction is not a minor legal detail, because it determines who is responsible for payment issues, who manages the security of the payment process, and what regulations protect the euro payment circuit.
That relationship is neither hidden nor simplified: when communication requires it, it must be clearly identified who assumes that regulated role.
Asking each provider's support team directly, "Who issues this card and under what regulations does it operate?" is a simple way to get that information without relying on the fine print of an app store. If the answer is vague or the provider avoids naming the regulated issuer, it's a sign that you should investigate further before ordering the product. If you want to see firsthand how this model works in practice, you can order a Card from Bit2Me and directly review their published terms of issue.
Crypto-Euro conversion and fees: what to check before anything else
When you pay with cryptocurrencies, the card automatically converts the balance to euros at the market rate in effect at the exact moment of the transaction. This conversion process usually involves a transaction fee, which can vary depending on the currency, the country where the payment is made, and whether it's an online purchase, a physical payment, or an ATM withdrawal. The applicable cryptocurrency-to-euro conversion fee can be found at [website address missing], and it's also advisable to check if there are different fees for transactions in currencies other than the euro or for ATM withdrawals outside the eurozone.
A common mistake when comparing crypto cards is focusing solely on the advertised fee and not the conversion spread, which is the difference between the actual market price and the effective exchange rate. A card with a seemingly low fee might compensate with a wider spread, so the real cost ends up being similar to or even higher than a card with a higher nominal fee. Explicitly requesting this information from the provider, and not just relying on the figure displayed on the landing page, is a sensible part of any serious selection process.
It's also unwise to assume that the conversion fee is fixed forever: current terms and conditions can change, and some providers apply specific exceptions to certain assets or wallets. No specific figure should be taken as fact without verifying it directly in the terms and conditions published by each institution, and even less so without taking it from a third-party comparison article without verifying the source. Saving the link to the current terms and conditions of the card you ultimately choose is a simple habit that prevents surprises later on.
Cashback and conditions: the fine print that changes the experience
Cashback is usually the most visible selling point in crypto card advertising, but it's also the most nuanced in practice. The cashback percentage almost always depends on variables such as the user's level within the loyalty program, the amount accumulated during the month, and the type of purchase made. No cashback program should be presented as a fixed and identical right for all users, because in practice, almost none of them work that way.
In addition to the percentage, it's worth checking which asset the reward is credited to, whether there's a monthly limit, and if that limit changes depending on the user's level within the program. Cashback credited to a token within the ecosystem itself isn't equivalent to cashback credited directly in euros, and this difference affects the actual value you receive based on how you use the card. These conditions determine whether the cashback is a relevant incentive for your usual spending habits or if, in practice, it only applies to a small percentage of your everyday purchases.
Asking about these conditions in writing before deciding avoids surprises that are only discovered when reading the full terms and conditions, something very few users do before applying for a card. Always compare cashback within the overall context of the card, not as an isolated factor: a proposal with moderate cashback but clear fees and limits can be more advantageous in the long run than one with a more attractive percentage but difficult-to-meet conditions. This is precisely the kind of nuance that a serious evaluation based on objective criteria should capture.
Physical and virtual availability and usage limits
Not all crypto cards offer the same formats or geographic availability. Some are only available as virtual cards in certain markets, while others also include a physical card, compatibility with Apple Pay or Google Pay, and broader coverage within the European Economic Area. Before making a decision, check if your country of residence is included in the provider's list of supported markets, as the availability of the physical card often depends on both the country and the user's level within the program.
The issuance of a virtual card is usually available more quickly than a physical one, which may require postal delivery and, in some cases, an associated cost depending on the user's level and the destination country. If your priority is to start using your crypto balance for online payments as soon as possible, the availability of the virtual version is as important a factor as cashback or conversion fees. However, if you regularly need to pay in physical stores, confirm the actual delivery times before assuming the card will be operational immediately.
Usage limits are another point that is rarely communicated as clearly as cashback in advertising. The current spending limits, ATM withdrawal limits, and number of cards per user should be reviewed before assuming that a card will cover any spending pattern seamlessly. A card designed for everyday purchases of average value is not always designed for higher-volume transactions or intensive use at ATMs outside the Eurozone.
Security: what guarantees to look for in the issuing entity
The security of a crypto card depends not only on the app that manages it, but also on the robustness of the underlying payment infrastructure. A regulated electronic money institution is subject to supervision, obligations regarding the safeguarding of euro funds, and a dedicated support channel for issues related to the card's operation. Verifying that this channel exists, and that the issuing entity is explicitly identified in the product terms and conditions, is a security criterion as important as any feature within the app.
For everyday use, look for features like activating and deactivating the card from the app, two-factor authentication (2FA) for sensitive transactions, and clear visibility of your transaction history. These basic security features should be available regardless of the brand you ultimately choose, and their absence is a more useful red flag than any generic security promise. The ability to immediately block the card from your phone if it's lost or used suspiciously is also a key factor.
No card, crypto or traditional, can be presented as immune to all risk, and any provider that makes such an absolute claim should raise more questions than it answers. What can be objectively assessed is whether the provider complies with the transparency requirements of the European regulatory framework and whether it offers effective controls against misuse. This combination of verifiable regulation and functional controls is, in practice, the best approach available to ensuring the security of any crypto card in Spain.
Quotable checklist: the questions you should ask yourself before choosing the best crypto card in Spain
With the criteria explained above, this checklist functions as a neutral template that you can apply to any crypto card you are evaluating, including the one from Bit2MeIt does not replace reading the terms and conditions of each provider, but it does help to structure what questions to ask and in what order to ask them.
- Who issues the card and what regulated electronic money entity backs the payment processing?
- What type of crypto-euro conversion applies, what commission does the provider publish, and is there an additional spread?
- What percentage of cashback does it offer, in what asset is it credited, and what are the monthly limits or conditions?
- Is it available in physical and digital format in your country of residence, and what are the release dates?
- What spending limits, ATM withdrawal limits, and number of cards per user does the provider apply?
- What support channel is available for issues specifically related to payment, and not just the app?
This list is intentionally extensive because each question corresponds to a different objective criterion, not an opinion on which brand is more appealing. Using it as a starting point allows you to build your own crypto card comparison without relying on external rankings or purely promotional arguments, and it works equally well whether you apply it to a single option or use it to evaluate several simultaneously.

Frequently asked questions about crypto cards in Spain



 Author