Essential Points
- Taxation of Staking: These returns are included in the savings tax base as income from movable capital, taxed according to the market value of the digital asset at the precise moment of its receipt.
- Taxes on Airdrops: Capital gains that do not derive from a transfer are considered; the recipient must declare the total value of the token at the time of receipt, assuming the risk of subsequent volatility.
- Information Obligations: Form 721 is mandatory in 2026 for balances on foreign platforms exceeding €50.000, while the DAC8 directive ensures that the Tax Office receives automatic data on your transactions.
- Accounting Management: It is vital to apply the FIFO criterion and keep a thorough record of each transaction, since network commissions (gas fees) can be deducted to optimize the final tax burden.
If you're waiting for the tax authorities to send you a letter before you start organizing your spreadsheets, you're too late. In 2026, with the tax agency's tracking infrastructure fully operational and the European DAC8 directive fully integrated, anonymity for income derived from crypto assets is a thing of the past. The excuse of "I didn't know how to declare it" is no longer valid.
Many users still see staking as a passive income stream similar to dividends, while airdrops are perceived as "free money." Wrong. For tax purposes, every token that lands in your wallet has a price tag and a specific box on your income tax return. Do you really know how staking is declared, or if that token you received for using a DeFi protocol will require you to pay taxes before you even sell it? Let's break it down.
Staking: A steady flow of obligations
The act of lock your tokens or stake Securing a network is not just a technical matter; it's a financial transaction with immediate repercussions. The tax authorities are clear that the profits obtained through the validation or delegation of assets are considered income from movable capital. In other words, they are taxed under the savings income tax base, just like interest from a bank account.
The critical point here is the accrual date. You don't pay taxes when you sell the tokens for euros, but rather the precise moment you have access to those new assets. If your node generates rewards every day, you have 365 different acquisition values to record. Is it an administrative nightmare? Absolutely.
Therefore, relying on exchanges that don't provide detailed tax reports is like buying a ticket to an audit. The rule is clear: the market value at the time of receipt determines the acquisition cost for future sales.
 Certificate
Airdrops: When free things come at a price
Cryptocurrency airdrop taxes are perhaps the most contentious issue. Unlike staking, where there is a deposit "activity," airdrops are generally considered capital gains that do not result from a transfer. They go directly into the general tax base if considered a prize, although the prevailing interpretation for diversified operations is that they form part of the savings base as a capital gain without prior transfer.
Imagine you receive a token from a new Layer 2 protocol. At that moment, the asset is worth €2.000. You must declare it on your current year's tax return, even if the token's value drops by 90% the following month and you decide not to sell. The liquidity risk is real: you could end up paying taxes on a valuation that no longer exists. Does this make fiscal sense? It's debatable, but it's the law. You could only offset that loss if you sell the asset and realize the capital loss.
Comparison: Where does each operation fit in?
To avoid getting lost in the terminology, this table summarizes the classification that the Spanish administration applies to the most common operations:
| Concept | Tax Rating | Tax Base | Taxation Time |
|---|---|---|---|
| Staking (Rewards) | Performance of Movable Capital | Savings (19% – 28%) | At the time of payment |
| Airdrops | Capital Gain | Savings (19% – 28%) | At the time of reception |
| Token sale | Capital Gain/Loss | Savings (19% – 28%) | At the time of the exchange or sale |
| Loans (Lending) | Performance of Movable Capital | Savings (19% – 28%) | Upon receiving the interest |
Model 721 and the end of the gray areas
By now, you should know that Form 721 is not a suggestion. If the value of your digital assets on foreign platforms exceeds €50.000 as of December 31st, filing is mandatory. Failing to comply by 2026 is essentially putting yourself in serious trouble. The Spanish Tax Agency cross-references data with the main European and global platforms.
Do we really need this level of control? Perhaps not for the small investor who simply wants to protect their savings from inflation, but the regulations don't distinguish between a software enthusiast and an institutional whale. Transparency is the price of mass adoption. If your tokens are in a hardware wallet (self-custody), the 721 obligation disappears (since they are not "abroad," but under your physical control), but the obligation to declare the income they generate on your income tax return remains.
Optimization and the challenge of the FIFO method
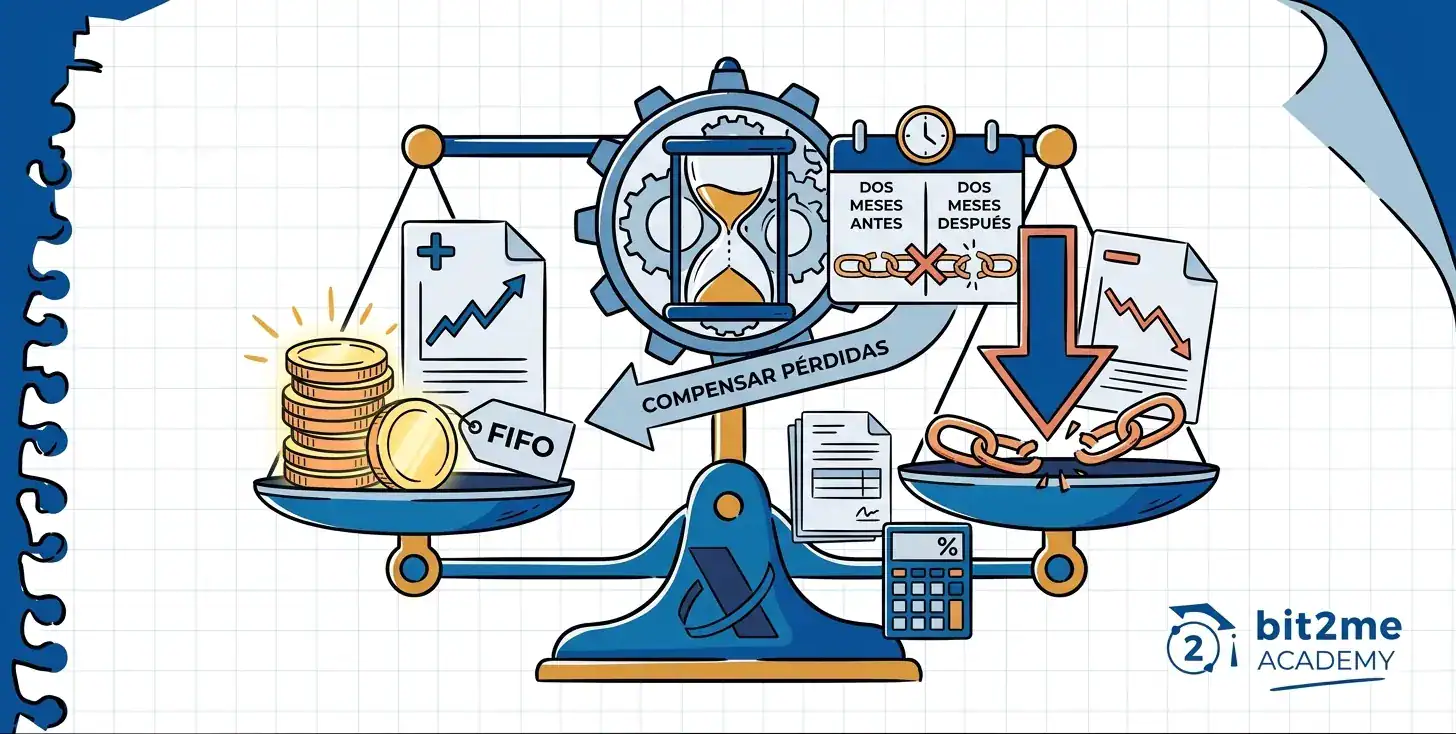
The use of the FIFO (First In, First Out) method is mandatory in Spain. This means that the first tokens you bought are the first ones you sell for profit calculation purposes. In staking operations where you constantly receive fractional amounts of assets, manual calculation becomes impossible.
A common mistake is failing to deduct expenses. If you've paid network fees (gas fees) to move your staking rewards, these amounts can reduce your earnings or increase your acquisition value. These aren't negligible sums if you operate on congested networks. Every euro of undeducted fees is a euro you're unnecessarily paying taxes on. Are you going to give money away to the government out of sheer accounting laziness? Use specialized software tools that automate this tracking; your peace of mind (and your wallet) will thank you.
FAQ: Taxation of Staking and Airdrops


 Author